What Credit Score Do You Need to Buy a New Construction Home in Colorado?
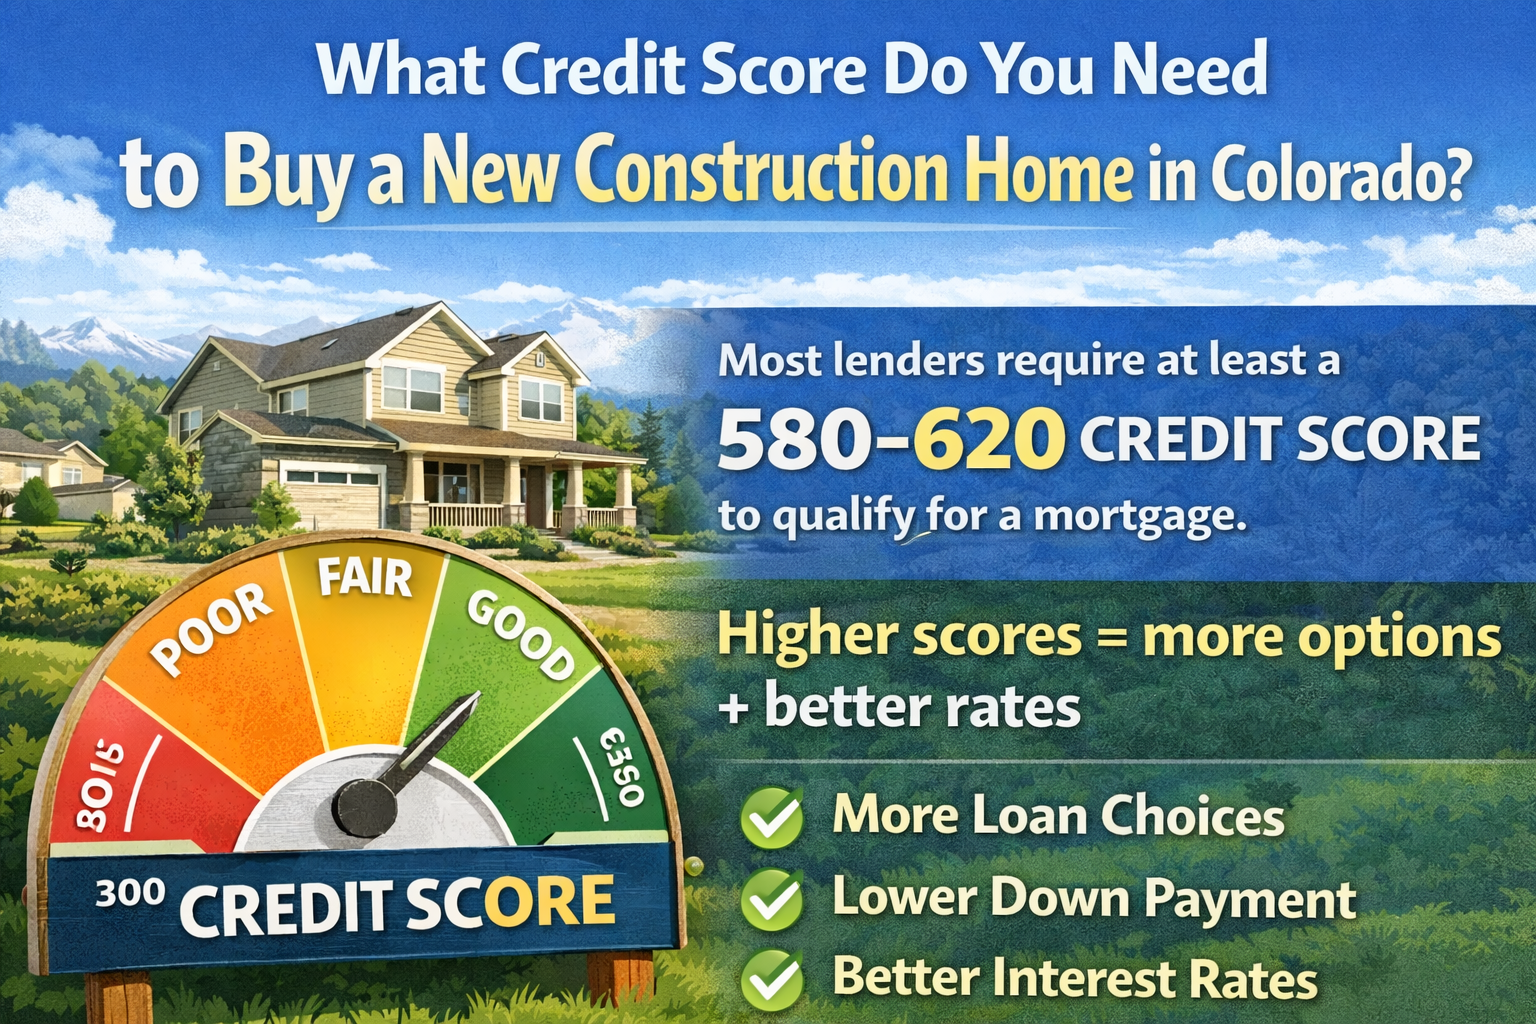
In most cases, you’ll need a minimum credit score between 580 and 620 to qualify for a mortgage—but higher scores unlock significantly better options.
Here’s a general breakdown:
- 580+ → Minimum for FHA loans (with higher down payment flexibility)
- 620+ → Typical minimum for conventional loans
- 680+ → Better interest rates and more favorable terms
- 740+ → Best rates and lowest monthly payments
Most buyers purchasing new construction in Northern Colorado fall in the 620–740+ range.
Thinking about buying new construction?
Get expert guidance on builders, incentives, and contracts — no pressure.
Why Credit Score Matters More for New Construction
Buying a new construction home is slightly different than buying resale—and your credit plays a bigger role than many buyers expect.
Builder Preferred Lenders
Many builders encourage (or incentivize) you to use their preferred lender.
Benefits may include:
- Closing cost assistance
- Interest rate buy-downs
- Upgrade credits
However, these incentives are often tied to:
- Credit score
- Debt-to-income ratio
- Loan type
If your credit score is lower, you may not qualify for the best incentives.
Rate Locks and Build Timelines
With new construction, your home may not be completed for 6–10 months.
This means:
- Your credit needs to remain stable during the build
- Lenders may re-check your credit before closing
- Rate lock options can depend on your credit profile
A higher score gives you more flexibility and protection.
Loan Types and Credit Requirements
Different loan programs have different credit score thresholds.
FHA Loans
- Minimum score: 580 (with 3.5% down)
- More flexible with credit history
- Popular for first-time buyers
Conventional Loans
- Minimum score: Typically 620
- Better rates with 680+
- Lower long-term costs compared to FHA
VA Loans (for eligible buyers)
- No strict minimum (typically 580–620 used by lenders)
- No down payment required
- Competitive interest rates
Jumbo Loans
- Typically require 700–740+
- Used for higher-priced homes
- Stricter financial requirements
How Your Credit Score Affects Your Monthly Payment
Your credit score doesn’t just determine approval—it directly impacts how much you pay every month.
Example Impact
- 620 score → Higher interest rate → Higher monthly payment
- 740+ score → Lower rate → Significant monthly savings
Even a small difference in rate can mean:
- Hundreds of dollars per month
- Tens of thousands over the life of the loan
Minimum Credit vs Ideal Credit
Just because you can buy with a lower score doesn’t mean you should.
Minimum Credit (580–620)
- Easier qualification
- Higher interest rates
- Fewer lender incentives
Ideal Credit (680–740+)
- Lower monthly payments
- Better loan terms
- More negotiating power with builders
If you’re close to a higher credit tier, it may be worth improving your score before buying.
What Lenders Look at Beyond Credit Score
Your credit score is important—but it’s only part of the equation.
Key Factors Include:
- Debt-to-income ratio (DTI)
- Employment history
- Income stability
- Down payment amount
- Cash reserves
Even with a strong credit score, these factors can impact your approval and loan terms.
Tips to Improve Your Credit Before Buying
If you're not quite where you want to be, small improvements can make a big difference.
Quick Ways to Boost Your Score
- Pay down credit card balances
- Avoid opening new accounts
- Make all payments on time
- Keep credit utilization low (under 30%)
- Check your credit report for errors
Even a 20–40 point increase can improve your loan options.
Common Mistakes to Avoid
Making Big Purchases During the Build
Avoid:
- Buying a car
- Opening new credit cards
- Financing furniture
These can impact your approval before closing.
Letting Your Credit Drop
Lenders often re-check credit before closing. A drop in score can delay—or even cancel—your loan.
Not Comparing Lenders
Even if a builder has a preferred lender, it’s smart to compare options.
Learn more here:
compare builders in Northern Colorado
How Credit Impacts Buying in Northern Colorado
In competitive markets like Fort Collins, Windsor, and Timnath:
- Higher credit = stronger offers
- Better financing = more builder incentives
- Lower payments = more purchasing power
If you're exploring
new construction homes in Northern Colorado
your credit score will directly influence what you can afford and where you can buy.
FAQ: Credit Score for New Construction Homes in Colorado
What is the minimum credit score to buy a house in Colorado?
Most lenders require at least 580–620, depending on the loan type.
Can I buy a new construction home with a 600 credit score?
Yes, but your options may be limited and your interest rate will likely be higher.
What credit score gets the best mortgage rates?
Typically 740+ will qualify you for the best available rates.
Do builders require higher credit scores?
Not necessarily, but their preferred lenders may have stricter requirements for incentives.
Should I wait to improve my credit before buying?
If you’re close to a higher tier, improving your score can save you significant money over time.
Final Thoughts
So, what credit score do you need to buy a new construction home in Colorado?
Technically, you can buy with a score as low as 580–620—but the real advantage comes with higher scores. The better your credit, the better your rate, monthly payment, and overall buying power.
If you're planning to buy in Northern Colorado, taking time to strengthen your credit can put you in a much better position—not just to qualify, but to get the best possible deal on your new home.