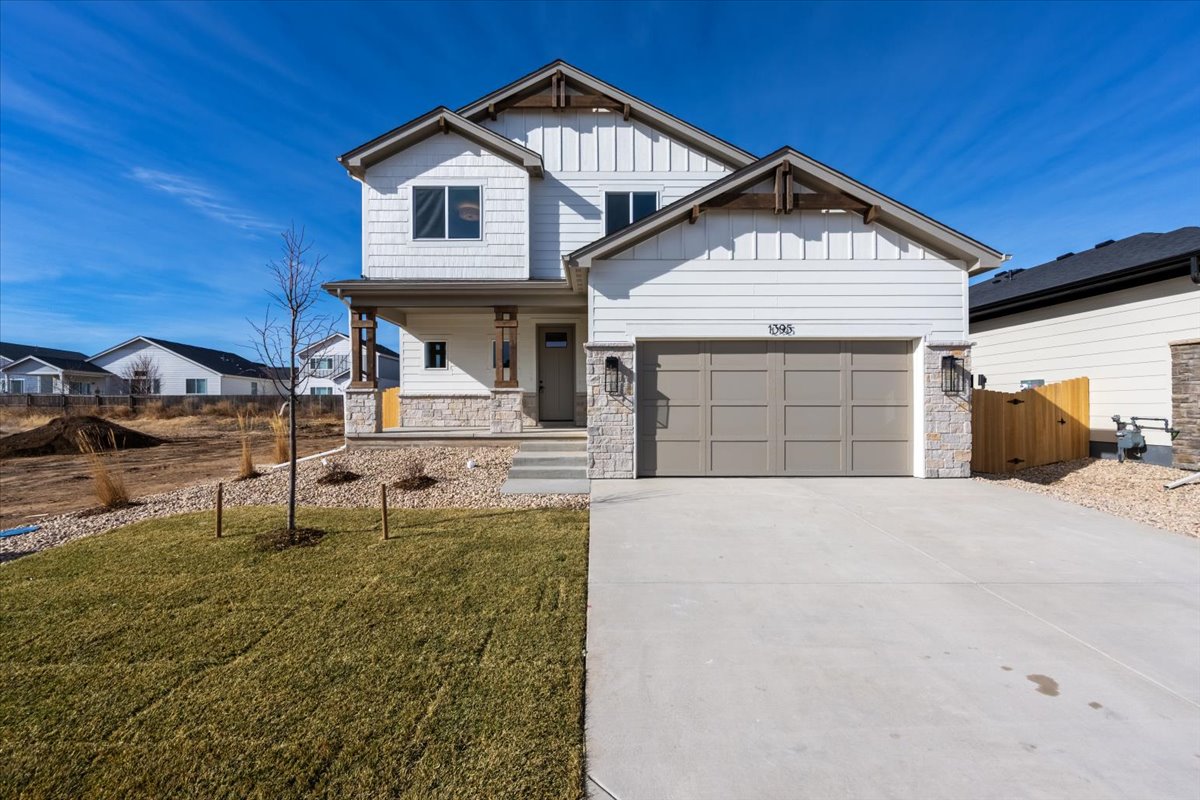
Fall is when Northern Colorado builders push hardest. They want finished homes sold and closed before year-end, and that's showing up as rate buydowns, closing cost help and outright price cuts. Some of these deals are excellent. Some look better in the ad than they do in your monthly payment.
I checked each builder's own website on October 17, 2026. Here's who's offering what, the fine print that matters, and how to tell which deal actually saves you the most.
Thinking about buying new construction?
Get expert guidance on builders, incentives, and contracts — no pressure.
The Deals at a Glance
| Builder | What they're offering | Fine print to know | Deadline |
|---|---|---|---|
| LGI Homes | Up to $50,000 in combined savings on select move-in ready homes, with rates as low as 4.99% (5.864% APR) | The 4.99% rate is an FHA/VA 5/1 ARM: fixed for 5 years, then adjustable | Sign and close by Nov. 14, 2026 |
| Hartford Homes | 3.99% for years 1–2, then 4.99% fixed for years 3–30 (FHA/VA), or 5.25% fixed (conventional) on select homes | Must use Hartford's preferred lender, Harmony Home Lending | Contract by Oct. 31, close by Nov. 30, 2026 |
| D.R. Horton | Fall savings event on select homes | Savings vary by home and are typically tied to DHI Mortgage | Ends Nov. 1, 2026 |
| Richmond American | 4.999% (5.737% APR) FHA 30-year fixed on select homes | Select homes only; ask which ones qualify | No end date posted |
| Meritage Homes | Up to $5,000 in closing costs plus fixed rates as low as 4.99% (5.09% APR) on select Colorado homes | Requires Meritage's preferred lender and closing agent; closing credit can't exceed 3% of the base price | No end date posted |
| Risewell Homes | 3.99% (7.129% APR) fixed for the first 5 years, plus a no-cost refinance | The APR is the tell: the rate adjusts after year 5 | No end date posted |
| Windmill Homes | Up to 5% of the purchase price toward a rate buydown, closing costs or both | Move-in ready homes, including Sunfield in Milliken | No end date posted |
| Baessler Homes | Up to $15,000–$20,000 in seller concessions, depending on the community | Must use Baessler's lending partners | No end date posted |
| Lennar | Rate buydowns and closing cost help on select homes | Only when you finance with Lennar Mortgage; amounts vary by home | Varies |
Hartford also announced up to $40,000 "Your Way" on select to-be-built Story Collection homes at Prairie Song in Windsor and Trailside in Timnath in early October. It isn't posted on Hartford's website, so confirm it's still available before you count on it.
Offers change fast, sometimes weekly. Risewell's offer changed in the last two weeks alone. Always confirm the current terms with the builder before you sign.
How to Read Builder Incentives Like a Pro
1. Check whether the rate is fixed or adjustable
A low rate gets the headline, but the loan type decides your long-term payment. LGI's 4.99% is a 5/1 ARM, and Risewell's 3.99% shows a 7.129% APR, which tells you the rate doesn't stay at 3.99%. Hartford's offer starts at 3.99% for two years, then settles at 4.99% fixed for the rest of the loan. Ask for the payment in year 1, year 3 and year 6.
2. Compare the builder's lender against an outside lender
Almost every incentive requires the builder's preferred lender. That can be a great deal, but get a second quote anyway. Sometimes an outside lender's rate plus a price reduction beats the builder's package.
3. Do the math on a price cut vs. a rate buydown
A $20,000 credit can lower your rate or your price. A lower rate cuts your monthly payment now. A lower price lowers your loan balance, and possibly your property taxes. If you plan to refinance or sell within a few years, the price cut often wins.
4. Watch the deadlines
Most fall deals require you to close by a set date, usually in November. That means move-in ready or nearly finished homes only. If you need a to-be-built home, ask what incentive applies to a later closing.
5. Get every incentive in writing
The incentive should be written into your purchase contract, with the dollar amount and what it can be used for. Verbal promises from a model home don't carry over.
Which Deal Fits You?
- Lowest payment in the next few years: Hartford's 3.99% start or Risewell's 3.99% for 5 years, if you're comfortable with the later rate.
- Biggest total savings on a move-in ready home: LGI's up to $50,000 event, if you can close by Nov. 14.
- Flexibility to choose: Windmill's up to 5% or Baessler's concessions, which you can put toward the rate, closing costs or both.
- A 30-year fixed rate from day one: Richmond American's 4.999% FHA fixed or Hartford's 5.25% conventional fixed.
Don't forget the metro district. A great rate can be offset by a high mill levy, so check it with our metro district calculator.
Let Me Do the Fine-Print Work
Builder incentives are where buyers leave the most money on the table, and the builder pays my fee, so it costs you nothing to have me in your corner. Bring me in before your first model home visit and I'll compare offers side by side, run the payment math, and negotiate the incentive into your contract.
Compare builders side by side, or text me at (970) 590-9656.
Mark Leavitt, RE/MAX Alliance · noconewbuilds.com
Sources
Offers checked on each builder's website on October 17, 2026: LGI Homes Make Your Move, Hartford Homes financing, D.R. Horton Northern Colorado, Richmond American Northern Colorado, Meritage Homes Northern Colorado, Risewell Homes Highlands Preserve, Windmill Homes available homes, Baessler Homes communities, Lennar Colorado.